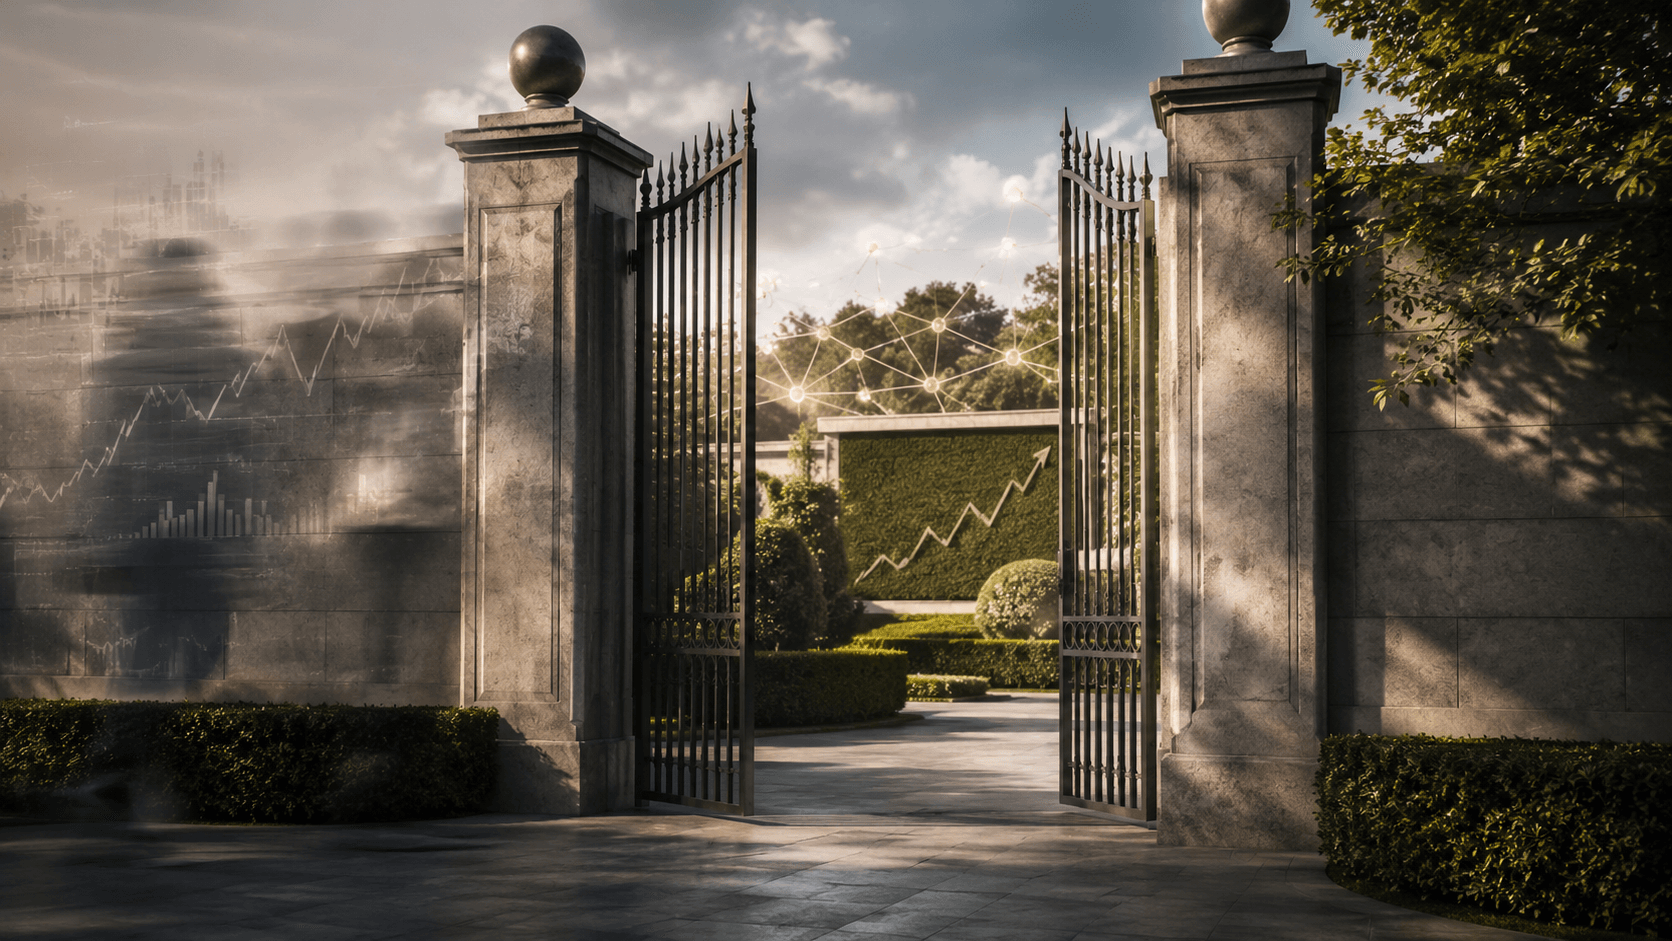
Without barriers to entry, earnings are a rumour. And you cannot value a rumour.
If you cannot see why a competitor would struggle to take a business's customers, you cannot see the future of its earnings. And if you cannot see the future of its earnings, you are not investing - you are speculating.
There is a moment, somewhere in the history of every great business, when someone decides to build a wall.
Not a physical wall. Something harder to see and harder to cross. A wall made of habit, of cost, of trust built over decades, of switching friction that makes leaving feel more painful than staying. A wall the customer barely notices- until a competitor tries to climb it.
That wall is the barrier to entry. And it is, in my view, the single most important thing a long-term investor needs to understand about any business they choose to own.
Everything else- the revenue growth, the margins, the management quality, the valuation multiple- rests on it. Without it, none of those other things are durable. Without it, you are not analysing a business. You are reading a story that someone else might rewrite tomorrow.
Earnings without a moat are a guess
Warren Buffett has spoken for decades about the economic moat - the structural advantage that protects a business from competition. But I want to make a more specific claim here, one that goes beyond the metaphor.
Barriers to entry are the precondition for predictable earnings.
Think about what a discounted cash flow model actually asks you to do. It asks you to project the cash a business will generate over five, ten, fifteen years- and then discount those cash flows back to today. The maths is straightforward. The hard part is the assumption buried inside it: that those future cash flows will actually exist.
If a business has no structural protection, that assumption is fragile. A well-funded competitor can enter. A cheaper alternative can emerge. A customer can leave without consequence. Each of those possibilities degrades your forecast. And a degraded forecast produces a meaningless valuation.
This is why I believe the first question in any investment analysis should not be about the price. It should be about the wall. Before I ask what a business is worth, I need to ask why it is allowed to keep earning.
Visa: a network that became a wall
Consider Visa.
At first glance, Visa looks like a payments company. It connects buyers and sellers. It processes transactions. It takes a small fee for doing so. The business model appears simple- almost mundane.
But look more carefully at what Visa actually built, and something remarkable emerges.
Visa's barrier to entry is not a patent or a government licence or a proprietary technology that could be replicated with enough capital. Its barrier is a network- and the network works precisely because everyone is already on it.
Merchants accept Visa because cardholders carry Visa. Cardholders carry Visa because merchants accept it. Each new participant in the network makes the network more valuable for every other participant. This is the logic of network effects: the product improves not through investment, but through adoption.
And here is the critical point for investors: a competitor does not need to build a better product to lose. They need to build a product good enough to convince both merchants and cardholders to switch simultaneously. Not one. Both. That is a near-impossible coordination problem - and Visa has never had to solve it, because it is the incumbent.
This is why Visa's operating margins have remained exceptionally high for decades. This is why its earnings are among the most predictable of any large business in the world. This is why analysts can model its cash flows with unusual confidence ten years into the future.
The network is the wall. And because the wall is real, the valuation is real.
The question behind the valuation
I have found, over time, that the most revealing question I can ask about any business is a simple one: why would a well-capitalised, intelligent competitor choose not to take your customers?
Not cannot. Choose not to.
Because the most durable barriers are not the ones that make competition impossible- they are the ones that make competition irrational. The ones where a rational actor, surveying the landscape, concludes that the effort is not worth the return.
The spreadsheet will always produce a number. But the number is only as good as the structural reality underneath it.
Before the model. Before the multiple. Before the price target. There is a prior question- one that most people skip because the spreadsheet does not ask it.
What is the gate that stands between this business and the competition it would otherwise face?
Find the gate. Understand what it is made of, how old it is, who maintains it, and how much it would cost to break down. Only then does the garden behind it have a value worth calculating.
Because earnings without a barrier are a rumour. And no serious investor builds a portfolio on rumours.
Andrew Padoa